Aligning Risk Tolerance with Risk Capacity: A Practical Guide
Investors often face a critical disconnect between what they can financially afford to lose and what they can emotionally withstand. This guide targets individuals seeking to resolve the Risk Tolerance vs. Risk Capacity dilemma without relying on generic advice.
You will receive a step-by-step diagnostic framework to measure your objective financial limits against your subjective comfort level. The process focuses on identifying specific gaps that lead to panic selling or excessive conservatism.
By the end, you will have a clear understanding of your Time Horizon and Liquidity Needs, enabling a strategy that prevents Volatility from derailing your long-term goals. Start by defining your true constraints.
Defining the Gap: What You Can Take vs. What You Will Take
Risk Capacity is your objective financial ability to absorb losses without jeopardizing future goals. It is determined by hard metrics: income stability, total assets, liabilities, and your specific Time Horizon. This is the ceiling of what your financial structure can withstand.
Risk Tolerance is your subjective psychological willingness to endure Volatility. It reflects how you feel when portfolio values fluctuate, independent of what your bank account can handle.
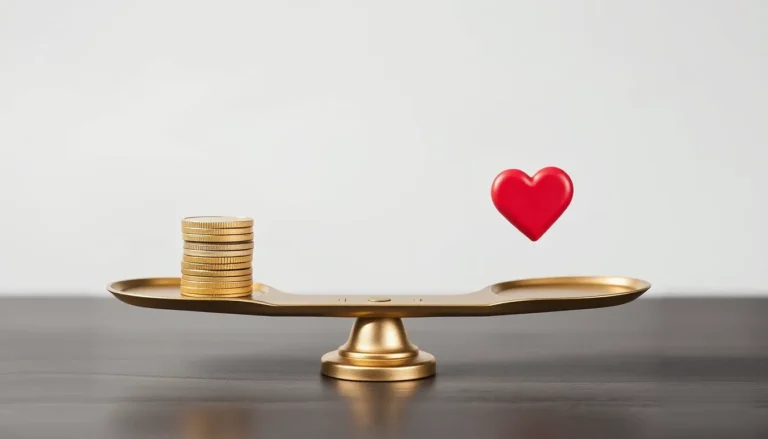
Aligning these two variables is critical because mismatches drive destructive behavior. If your Risk Tolerance is lower than your Risk Capacity, you are likely to panic-sell during downturns, locking in losses and missing recoveries. Conversely, if your tolerance exceeds your capacity, you may over-invest or take on debt, leading to severe financial distress when a Drawdown occurs.
Understanding this distinction prevents you from confusing comfort with capability. You must recognize that your emotional limit may be lower than your financial limit, or vice versa. By clearly separating what you *can* take from what you *will* take, you create the foundation for a strategy that respects both your psychological boundaries and your objective reality.
Step 1: Calculate Your Objective Risk Capacity
Start by quantifying your financial reality. List all total investable assets, stable income sources, and fixed liabilities. This baseline reveals how much cushion exists between your current spending and your net worth. Next, define your hard floor: the specific dollar amount you cannot afford to lose without compromising essential living standards or critical obligations. Any loss beyond this threshold triggers a lifestyle change, marking the limit of your Risk Capacity.
Then, specify your Time Horizon. When exactly do you need to access these funds? A shorter horizon reduces your tolerance for Volatility because you lack time to recover from market dips. Conversely, a longer horizon allows for greater exposure to Drawdowns, as time provides the opportunity for portfolio recovery.
Combine these factors to calculate your objective limit. The expected result is a specific percentage or dollar amount of portfolio volatility you can financially withstand. This figure represents the maximum risk you can carry without missing your financial goals or altering your standard of living. It is a cold, hard number derived from your Liquidity Needs and asset base, independent of your feelings. Use this metric as the ceiling for your investment strategy, ensuring your portfolio structure aligns with what your finances can actually support, not just what you wish they could.
Step 2: Assess Your Subjective Risk Tolerance
Now turn inward to measure your emotional resilience. This is your Risk Tolerance: the level of Volatility you can psychologically endure before acting irrationally. It is distinct from your financial capacity and often lower than you believe.
Confront this reality with specific hypothetical scenarios. Ask yourself: “If my portfolio dropped 20% in a single month, would I buy more, hold steady, or sell everything?” Be honest. Do not answer with what you think you should do, but what your gut reaction would actually be.
You must distinguish between your short-term “stomach” and your long-term “conviction.” Stomach is the immediate panic response to a Drawdown. Conviction is your belief in the asset’s future value. Many investors have high conviction but low stomach, leading them to sell at the bottom during a correction despite knowing the logic of their strategy. The expected result of this assessment is identifying your true emotional breaking point. Review your behavior during past market corrections. Did you stick to your plan, or did you react to fear? Your history is the most accurate predictor of your future reaction to stress. If your past behavior shows you panic when assets lose significant value, your subjective Risk Tolerance is lower than your objective Risk Capacity. Acknowledge this gap now to prepare for it later, ensuring your strategy accounts for your human nature rather than ignoring it.
Step 3: Identify the Mismatch and Its Consequences
Compare your calculated Risk Capacity from Step 1 with your assessed Risk Tolerance from Step 2. The distance between these two figures defines your mismatch. Understanding this gap prevents costly errors before market Volatility tests your resolve.
High Capacity, Low Tolerance: You can afford significant Drawdowns due to a long Time Horizon and low Liquidity Needs, but you psychologically reject them. The financial cost is underperformance; by staying in conservative assets, you sacrifice growth potential. The psychological cost is regret, knowing you left returns on the table while playing it safe.
Low Capacity, High Tolerance: You enjoy risk or ignore its impact, despite limited time or high cash needs. The financial cost is severe: excessive Volatility can deplete your portfolio before retirement, forcing early withdrawals or compromised goals. The psychological cost is anxiety and sleepless nights, as your emotional resilience fails when reality hits.
Identify which scenario describes you. If you are over-invested relative to your capacity, you are gambling with your future. If you are under-invested relative to your capacity, you are paying a fee for fear. Pinpointing this specific mismatch is the prerequisite for building a strategy that feels sustainable and performs adequately.
Step 4: Build a Strategy That Bridges the Gap
Bridging the Gap with Actionable Structure
Once you understand the mismatch, adjust your portfolio structure to match your actual limits. The goal is sustainability, not maximum return. A strategy that forces you to sell during a panic is a failed strategy.
If your Risk Capacity exceeds your Risk Tolerance, use a core-satellite approach. Allocate the majority of your assets to conservative holdings that soothe anxiety. Keep a small satellite portion in growth-oriented assets to participate in market upside. This structure acknowledges your emotional limits while preserving some growth potential.
If your Risk Tolerance exceeds your Risk Capacity, you must cap your exposure to volatile assets. Ignore your desire for higher returns. Limit risky investments to the level your financial reality allows. Consider your Time Horizon and Liquidity Needs when setting this cap. If you need cash soon, lower your allocation to volatile assets further.
Regularly review this alignment. Market conditions and personal circumstances change. Reassess your Drawdown limits annually. If your strategy requires you to ignore a significant loss to stay invested, it is misaligned. Adjust the mix to ensure you can hold through Volatility without breaking. This discipline prevents the emotional selling that often erodes long-term wealth. Focus on what you can sustain, not what you wish you could.
Common Mistakes That Break the Alignment
Even with a solid framework, specific errors can derail your alignment. Watch for these three pitfalls.
Confusing Age with Capacity
Using age as a proxy for Risk Capacity is a dangerous shortcut. A 50-year-old with substantial savings and no debt holds far more capacity than a 30-year-old burdened by high-interest debt. Your true capacity comes from your balance sheet and Time Horizon, not your birth year. Calculate your net worth to see where you actually stand.
Ignoring Liquidity Needs
You cannot wait out a market crash if you need cash soon. If you are saving for a house down payment due in two years, that money has strict Liquidity Needs. Treating it as long-term investment capital ignores the risk of a Drawdown hitting before your deadline. Segregate short-term goals from long-term portfolios to protect your cash flow.
Letting Recent Performance Dictate Tolerance
Your emotional state fluctuates with the market. Becoming overly aggressive after a bull run or panic-selling after a bear market means your Risk Tolerance is reactive, not structural. This whipsawing prevents consistent execution. Anchor your strategy to your objective capacity, not your current mood.